WHO · Core Audience
Core Audience Profile
Skews 25-44 Western males (60%); female share up from 30% to 39%; Millennials at 48%; BG3 drives massive new fan influx
52-Yr Classic Fantasy IP in Collab Boom; Core 25-44 Male Skew with Female Share Rising to 39%
Who · Where · Why Now
Skews 25-44 Western males (60%); female share up from 30% to 39%; Millennials at 48%; BG3 drives massive new fan influx
NA is core (50%+ revenue), EU is 2nd largest, East Asia is top growth · Dragonheir's 2.53M first-month CN downloads validate potential
50th-anniversary tailwind + collab boom (124 events in 2024-25) + WotC $2.2B annual revenue + strong licensing intent; 12-18 mo optimal greenlight window
Age cohorts · Gender split · Segment preferences
Rose from 30% in 2020 to 39% in 2023, growing ~3 ppts annually
Female share rose from 30% in 2020 to 39% in 2023, growing ~3 ppts annually
Males prefer Fighter/Paladin (power) + combat builds; females prefer Bard/Druid (social/support) + narrative-driven. Collab design must balance both aesthetics.
Payer · Decider · User
28-38 Western male core player, $300-800 annual spend
Spending profileRulebooks + dice + minis + D&D Beyond digital content; high ARPPU
Collab angleDeep RPG collabs, limited dice/minis merch, D&D Beyond integrated content
18-26 digital native, discovered D&D via Baldur's Gate 3
Spending profilePrefers digital spend (IAP / skins / Battle Pass), $100-400 annual spend
Collab angleShadowheart character skins, limited gacha characters, social-share cosmetics
20-35 CN/JP/KR mobile core user, $20-100 monthly spend
Spending profileHigh-frequency low-spend gacha, sensitive to limited/time-bound content
Collab angleSRPG collabs (Dragonheir model), D20 mechanic integration, time-limited campaign dungeons
30-45 parents + 6-14 kids, seeking screen-free family time
Spending profileEntry-friendly products (Starter Set $20-30 / LEGO D&D sets), $50-200 annual spend
Collab angleMinecraft D&D DLC mode, family co-creation content, educational simplified versions
Map shade = regional potential · 6-factor market scorecards below
Top pick for all-category collabs, deep integration
English regions first, DE/FR localization
Test via top mobile collabs; Dragonheir's 2.53M first-month downloads validated
Needs deep localization; D&D is niche under CoC dominance, leverage BG3 hype
Leverage MMORPG culture bridge; CoC also dominates KR TTRPG market
Follow NA pacing, English requires no localization
Heat bar = collab appearance frequency 1–5
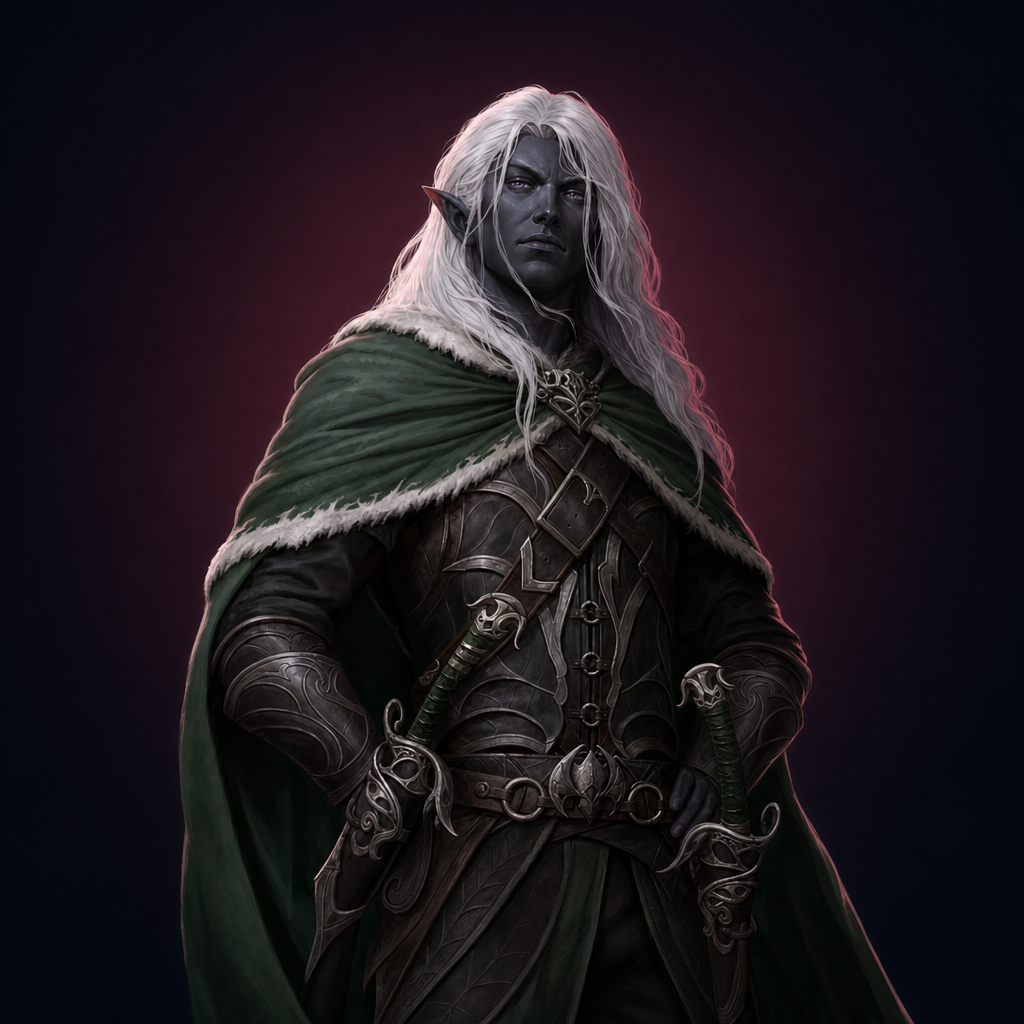
Highest collab appearance rate, highest East Asia recognition
PLAYPlayable Character / Summon
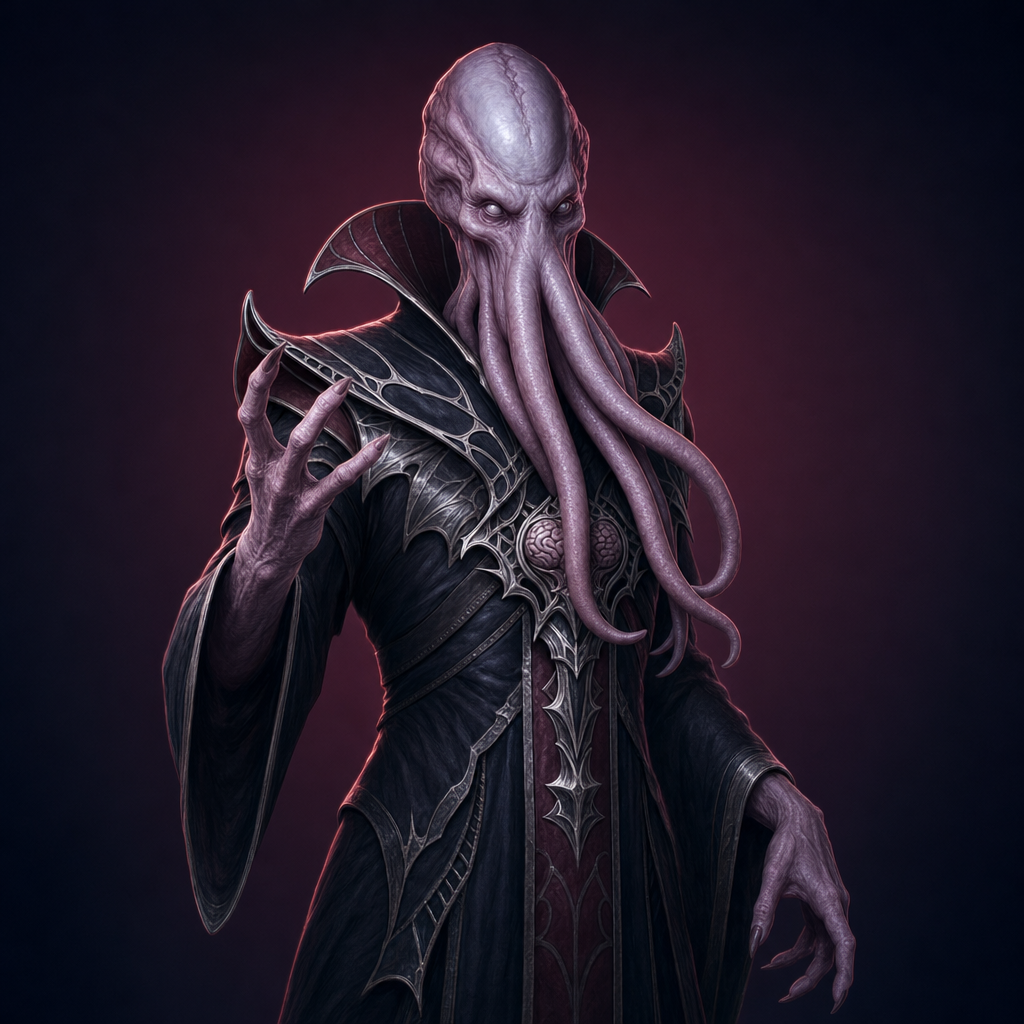
Skyrocketed recognition post-BG3, extreme visual impact
PLAYBoss / Cosmetic Skin
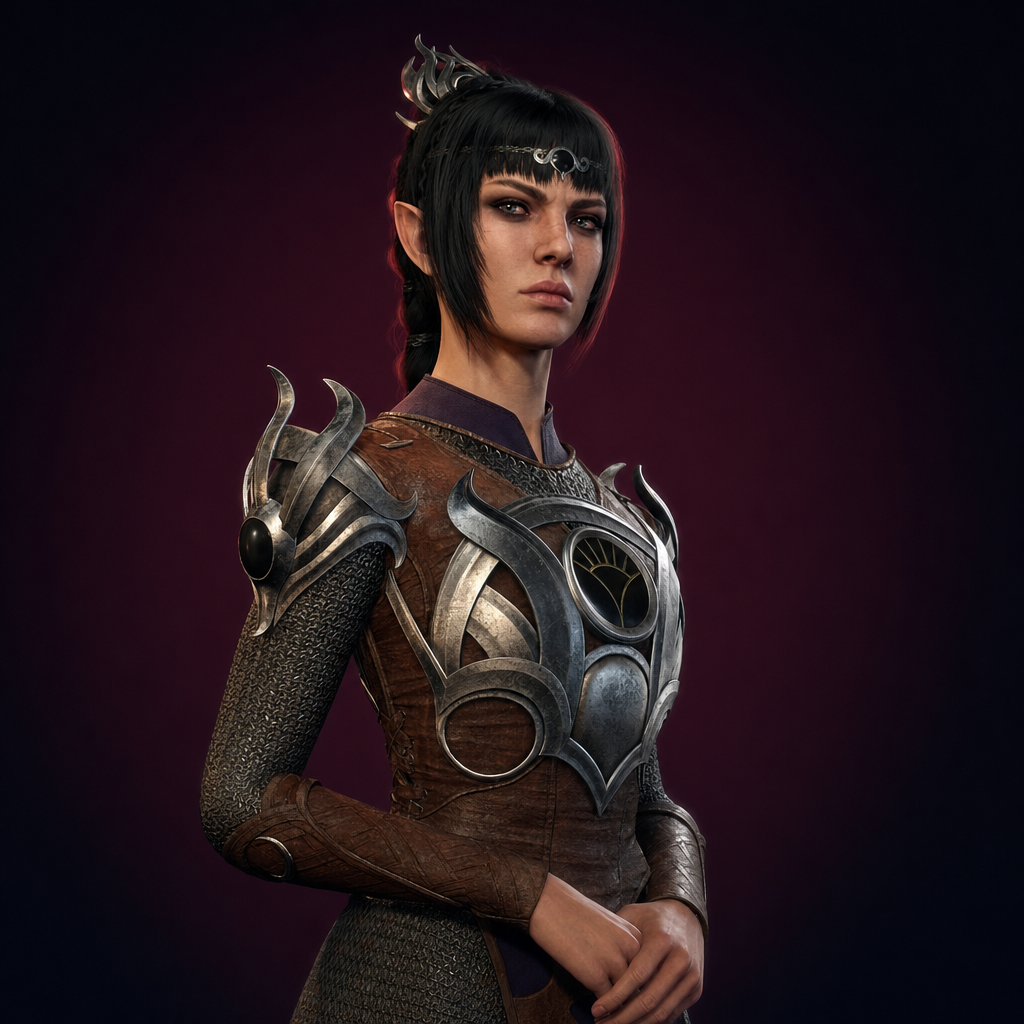
BG3 crossover effect, top pick for female players
PLAYGacha Character / Skin
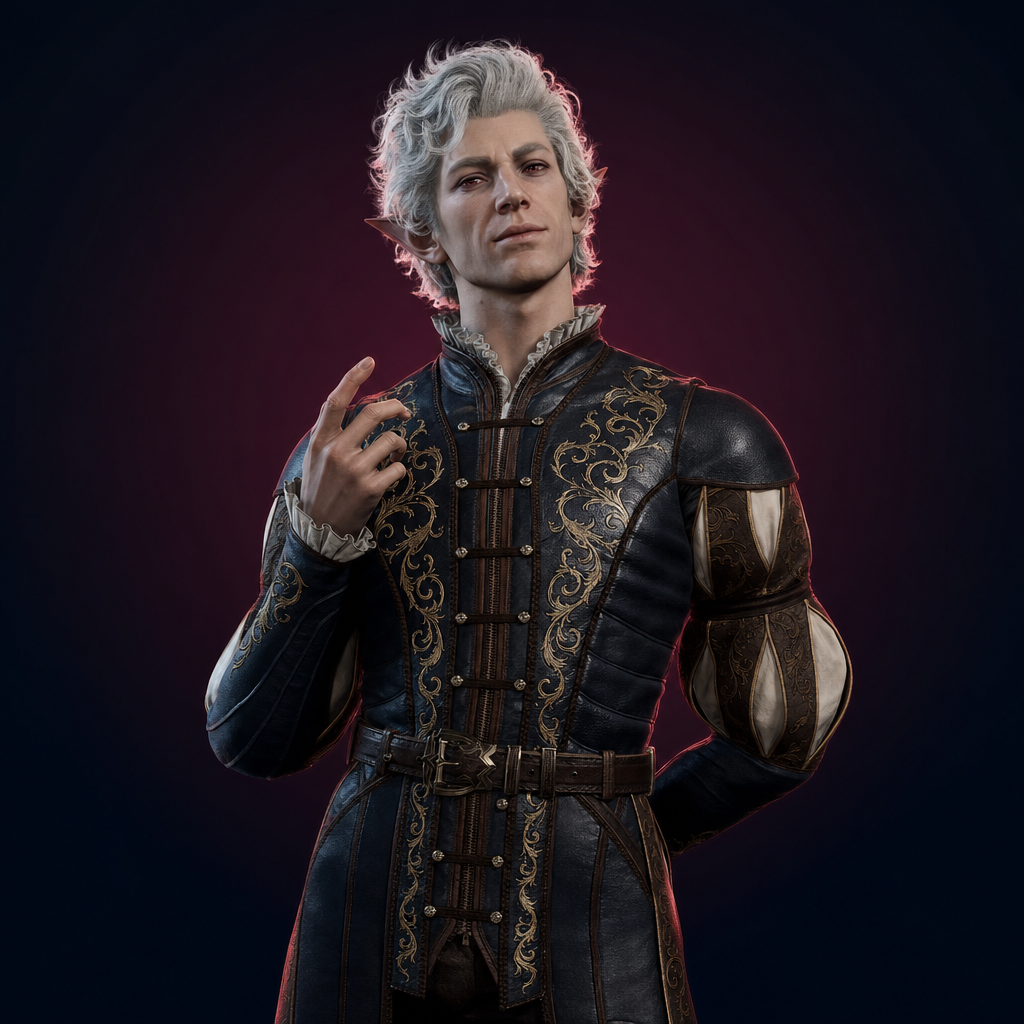
New-gen BG3 icon, high commercial value
PLAYGacha Character / Skin
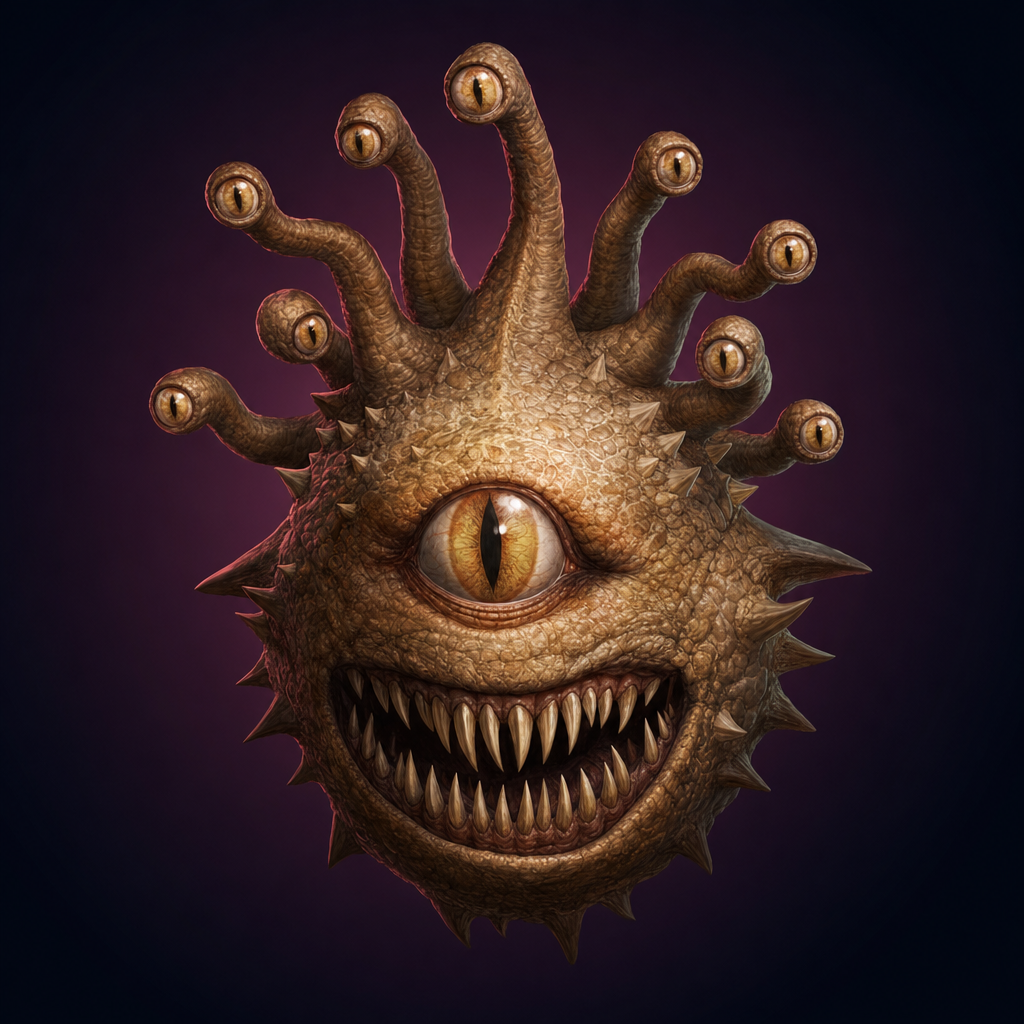
Extremely high visual recognition, ideal for boss design
PLAYBoss / Cosmetic Item
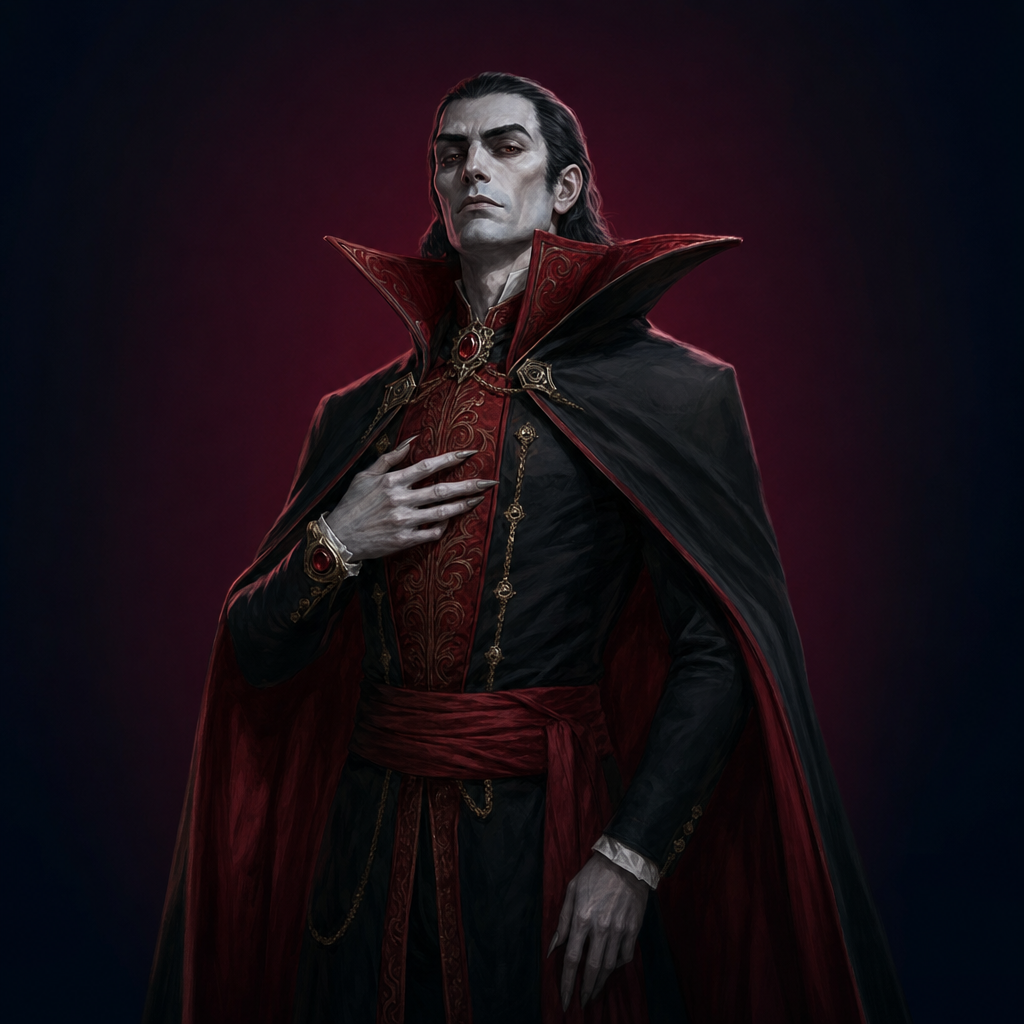
Gothic horror aesthetic, core fan favorite
PLAYCampaign Dungeon / Skin
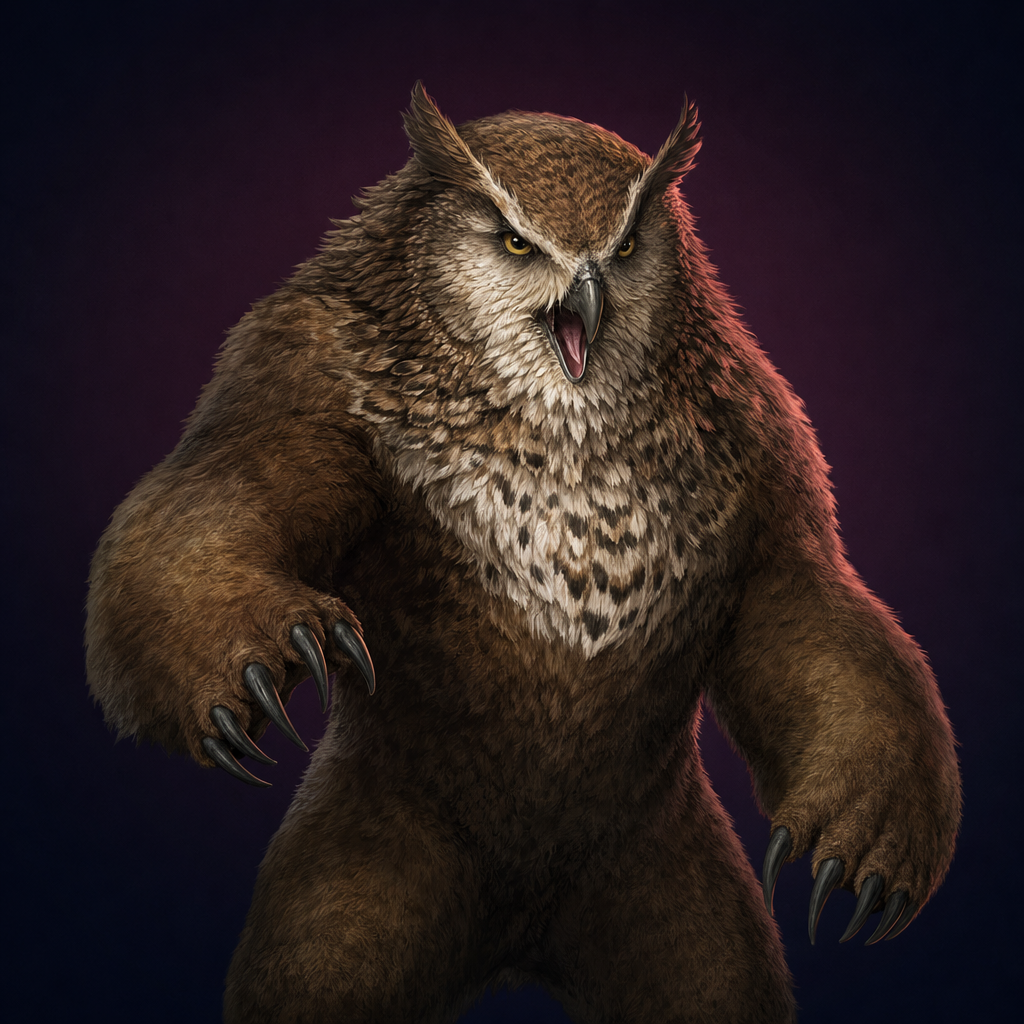
Cute + powerful, huge merch potential
PLAYPet / Mount
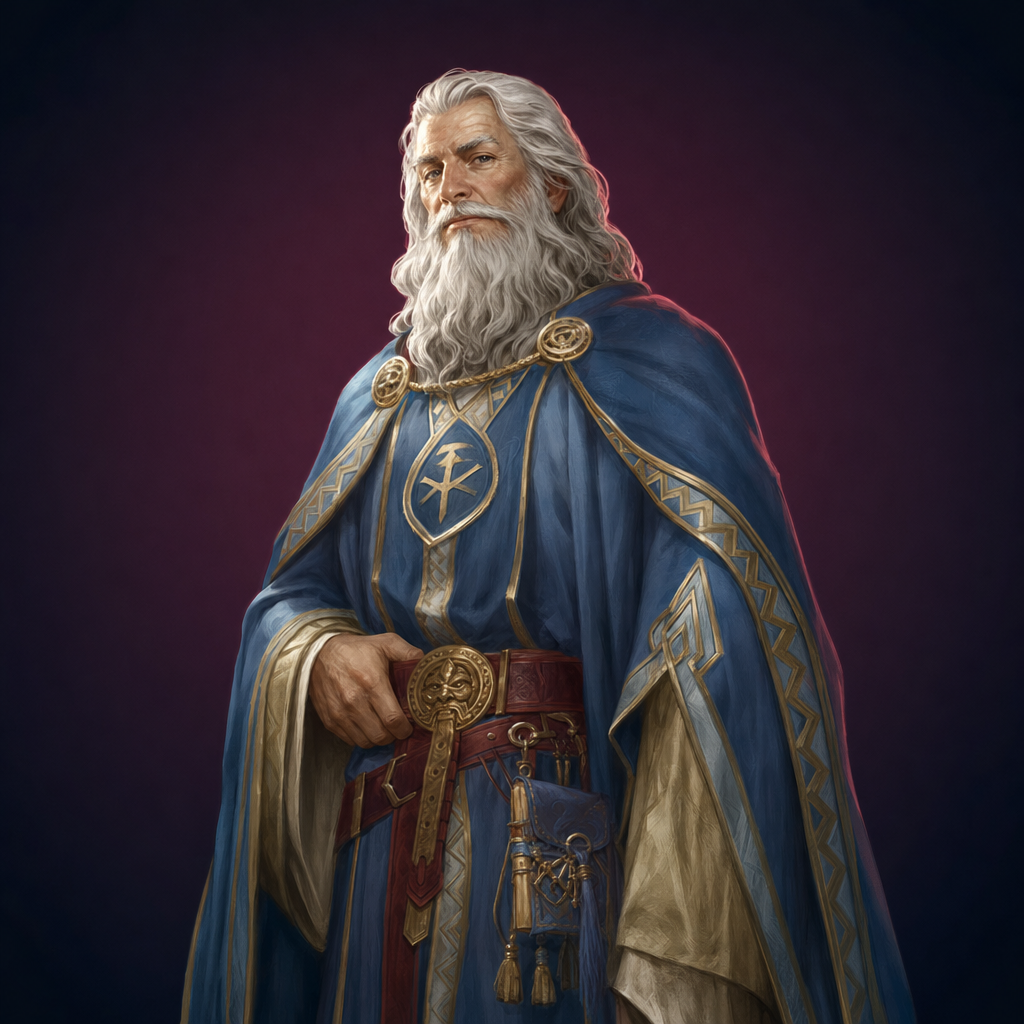
Core fan recognition, validated via Dragonheir collab
PLAYPlayable Wizard Character
Benchmark cases · Latest game collabs · Collabs per year
124 collab events in 2024-2025 (56% of total); IP is in its most intense collab boom in history
BG3 $90M licensing revenue covers Aug-Dec 2023; Dragonheir ¥110M is a bi-weekly estimate incl. Android (iOS:Android ≈ 1:2); WotC $2.2B includes D&D + MTG + Digital Games
Genre fit 1–5 · Emotional driver → Game system → Monetization
Natural fit; D&D is the RPG progenitor; BG3 validated the CRPG route
Perfect match for squad tactics + character building; validated by Dragonheir
MTG cross-IP collab validated; D&D card adaptations have precedent
Minecraft DLC validated sandbox + D&D narrative viability
Dark Alliance validated genre viability
Demeo Battlemarked validated VR tabletop + D&D deep integration
DbD collab validated D&D monsters in horror genre
Fortnite collab validated UGC island mode
RPG and SRPG are best fits (5/5); Sandbox / Card / VR validated (4/5); MOBA and Casual have lower fit (2/5)
No-goExcessive stat inflation breaking balance
No-goForced socializing or PVP stomping
No-goSkippable story or low-quality voice acting
No-goOverly aggressive gacha pay-to-win feel
2024 new rulebook + BG3 long-tail effect + digital ecosystem expansion put IP commercial value at its peak
Full coverage from AAA games (Minecraft DLC) to UGC platforms (Fortnite), lowering collaboration barriers
20M+ sales bring a 'digital entry' generation with much higher collab acceptance than traditional tabletop players
Dragonheir's 2.53M CN first-month downloads / ¥64.64M gross revenue proves D&D lore has commercial potential in China
BG3 characters like Shadowheart attract massive female players; collab design can expand female-oriented monetization
296 collab events vary in quality; a flood of low-quality collabs could dilute the brand
2023 OGL controversy proved massive community backlash power; any 'lore-breaking' changes risk large-scale boycotts
CN/JP/KR TTRPG markets are CoC-dominated, D&D is niche; D&D Beyond lacks JP/CN localization
Netflix's Forgotten Realms series was canceled in Sep 2026, hindering screen-based expansion
D&D 5E's 'de-stereotyping' adjustments to race/alignment alienated some veteran players, risking community fracture