WHO · Core Audience
18–34 G4 Nostalgic Women
Independent disposable income, high-ARPU paying engine, core monetization segment for game collabs
G4 Nostalgia Revival × China Game Collab Boom — 18–34 Women as Primary Monetization Anchor
Who · Where · Why Now
Independent disposable income, high-ARPU paying engine, core monetization segment for game collabs
China weekly rank #3; top-tier collabs with Honor of Kings / Game for Peace / Eggy Party already validated
G4 nostalgia revival × G5 content maturation × China game collab boom; Hasbro licensing stance markedly open
Age cohorts · Gender split · Segment preferences
G4 nostalgic audience with independent disposable income; core paying segment for game collabs
Surface female-skew, actual dual-gender complexity; game collab scenarios see female share rebound to ~55%
Female preference: Twilight / Rarity / Fluttershy; life-sim / dress-up / collection. Male preference: Rainbow Dash / Discord; competitive / strategy / meme
Payer · Decider · User
G4 nostalgic core women; highest-ARPU paying engine
Spending profileWilling to pay premium for limited skins/figures (¥50–300); high-frequency small spend + low-frequency big spend
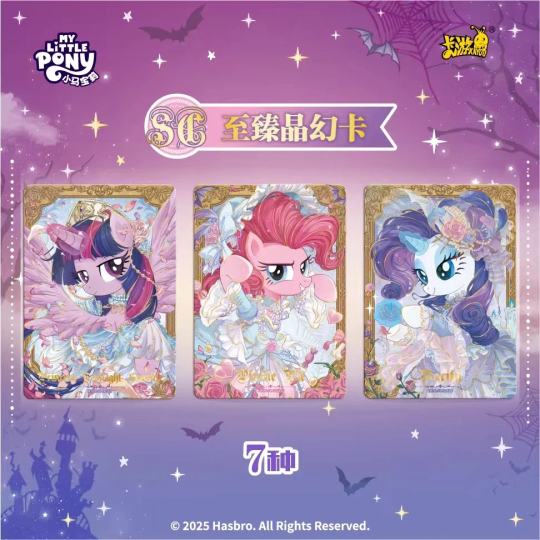
Collab angleGame limited skins, co-branded apparel, collectible cards, themed cafés
China Gen-Z card & designer-toy collector; social-currency driven
Spending profileHigh-frequency small spend (¥10–50/pack); willing to pay premium for rare cards
Collab angleTCG, blind boxes, in-game collection systems, social sharing mechanics
Young-family parents; intergenerational long-term value
Spending profileWilling to pay premium for educational products; cautious decision-making
Collab angleFamily mobile games, educational apps, toy sets, offline family experiences
Current core kids audience; largest base by volume
Spending profileSmall-amount high-frequency (allowance on cards/blind boxes); heavily influenced by peers/KOLs
Collab angleKids mobile games, Roblox experiences, cards, toys, animation content
Map shade = regional potential · 6-factor market scorecards below
Full-pipeline push: top-tier game collabs + cards + live experiences
Maintain Toys + Netflix + Roblox ecosystem; game collabs focused on Roblox/console
Stable toys + animation; test casual/female-skewed game collabs
Mobile-first; card + casual game collabs; Shopee/Lazada merch
Japan: test female-skewed game collabs; Korea: G5 content intro + casual games
Broad animation coverage; toys + cards as entry point; game collabs await infrastructure
Heat bar = collab appearance frequency 1–5
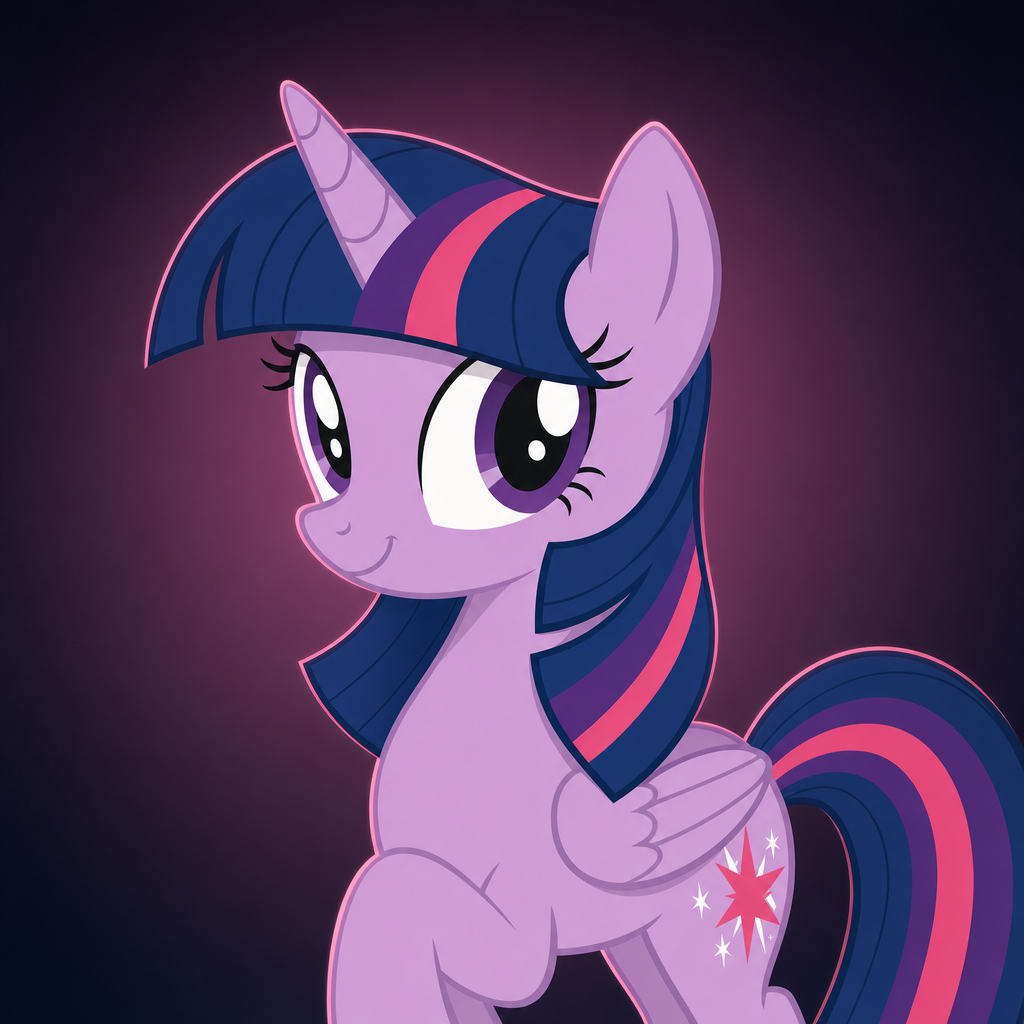
All-ages, universal appeal; cover character for nearly every collab
PLAYCover skin / protagonist aura
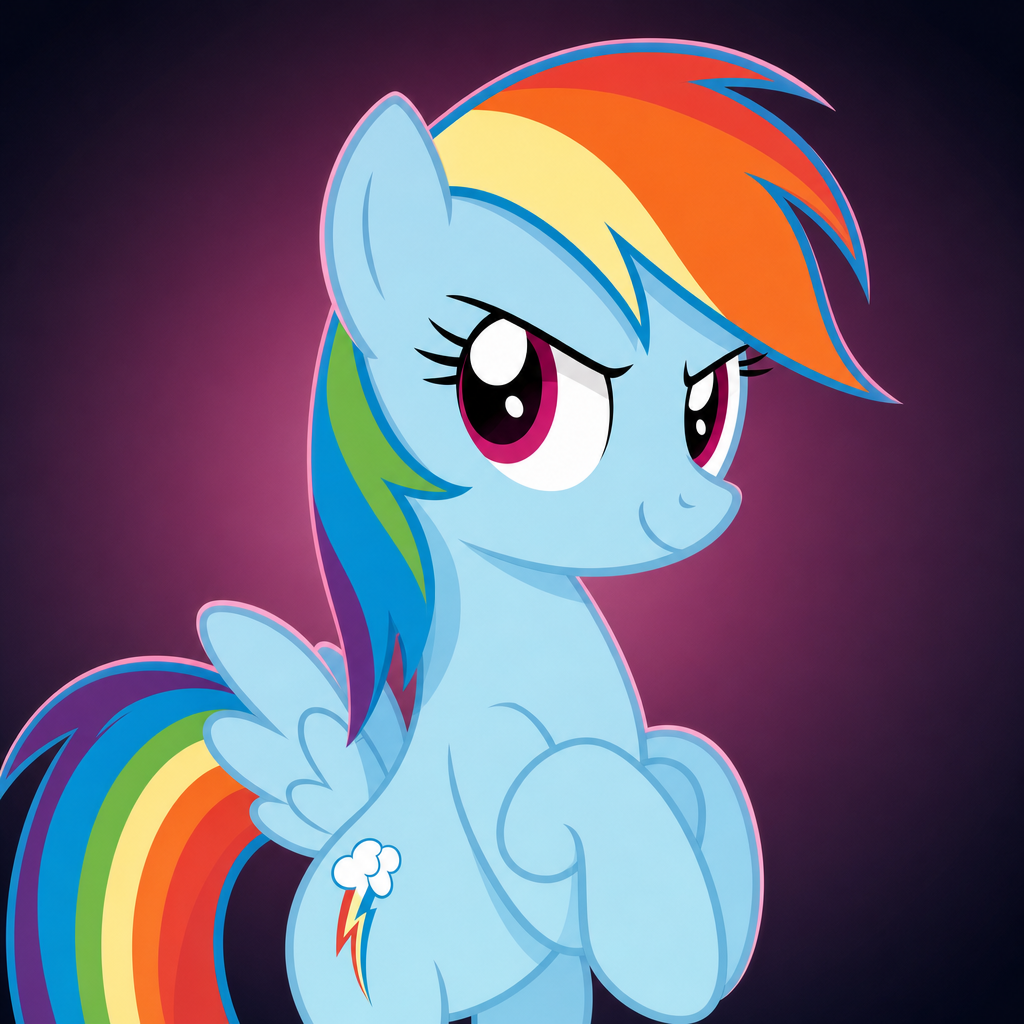
Slight male-audience preference; extremely high rainbow-color recognition
PLAYRacing / flight skills
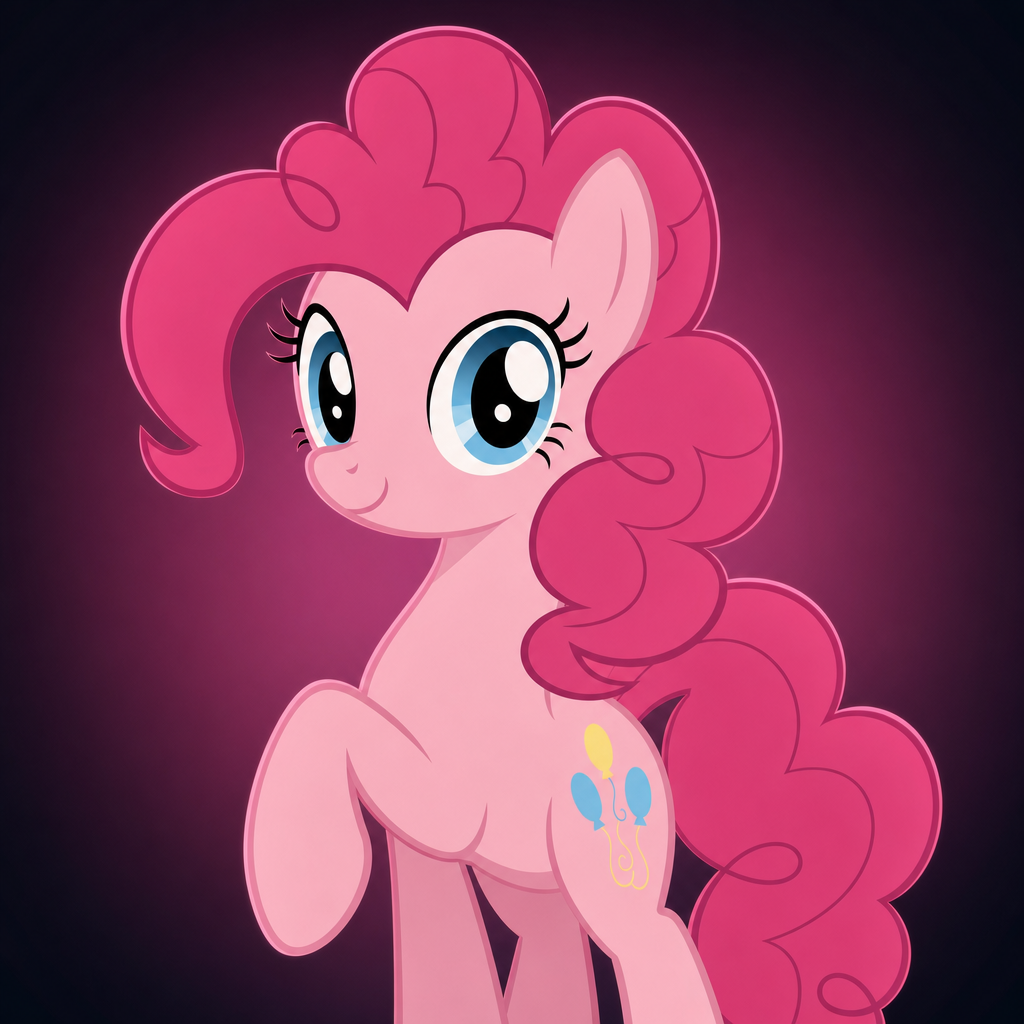
Preferred by Chinese women; strong TikTok/Douyin virality
PLAYParty / social events
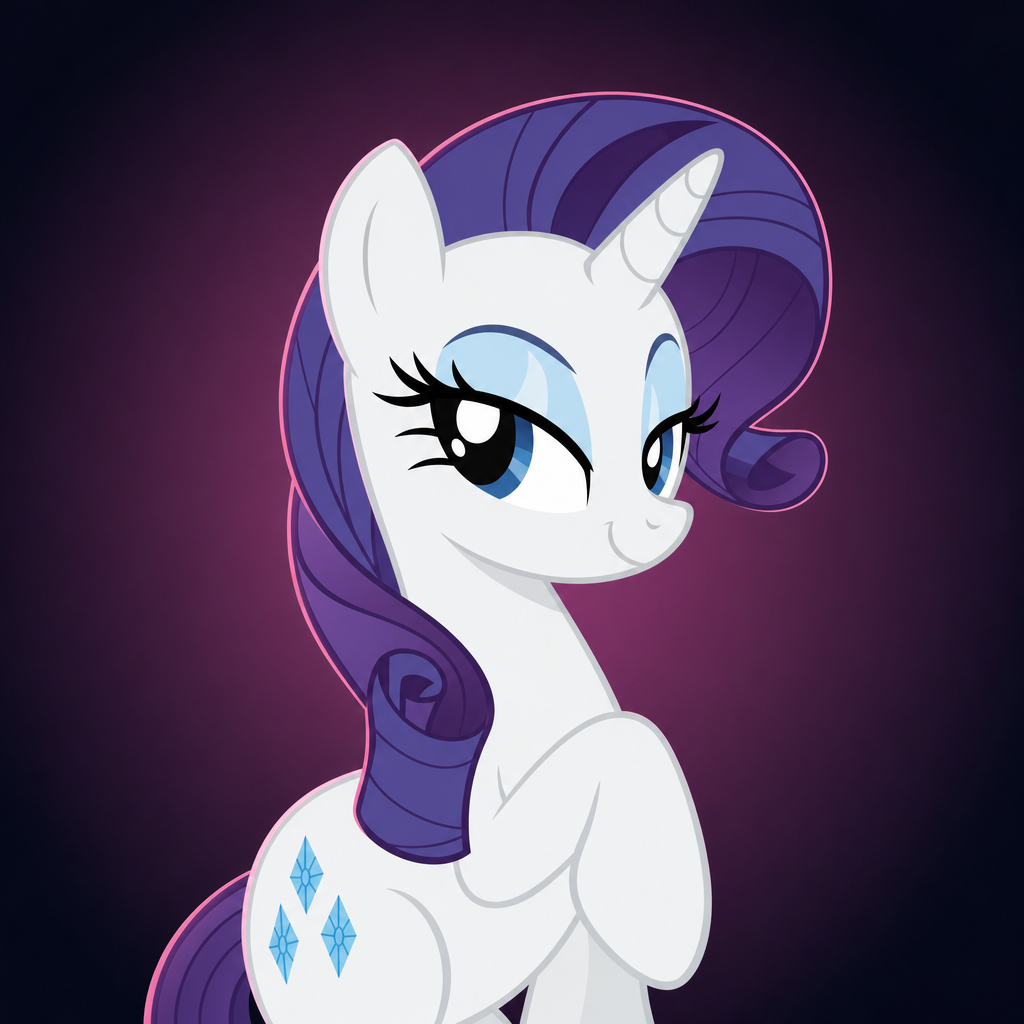
Core female-audience preference; top pick for dress-up collabs
PLAYDress-up / fashion system
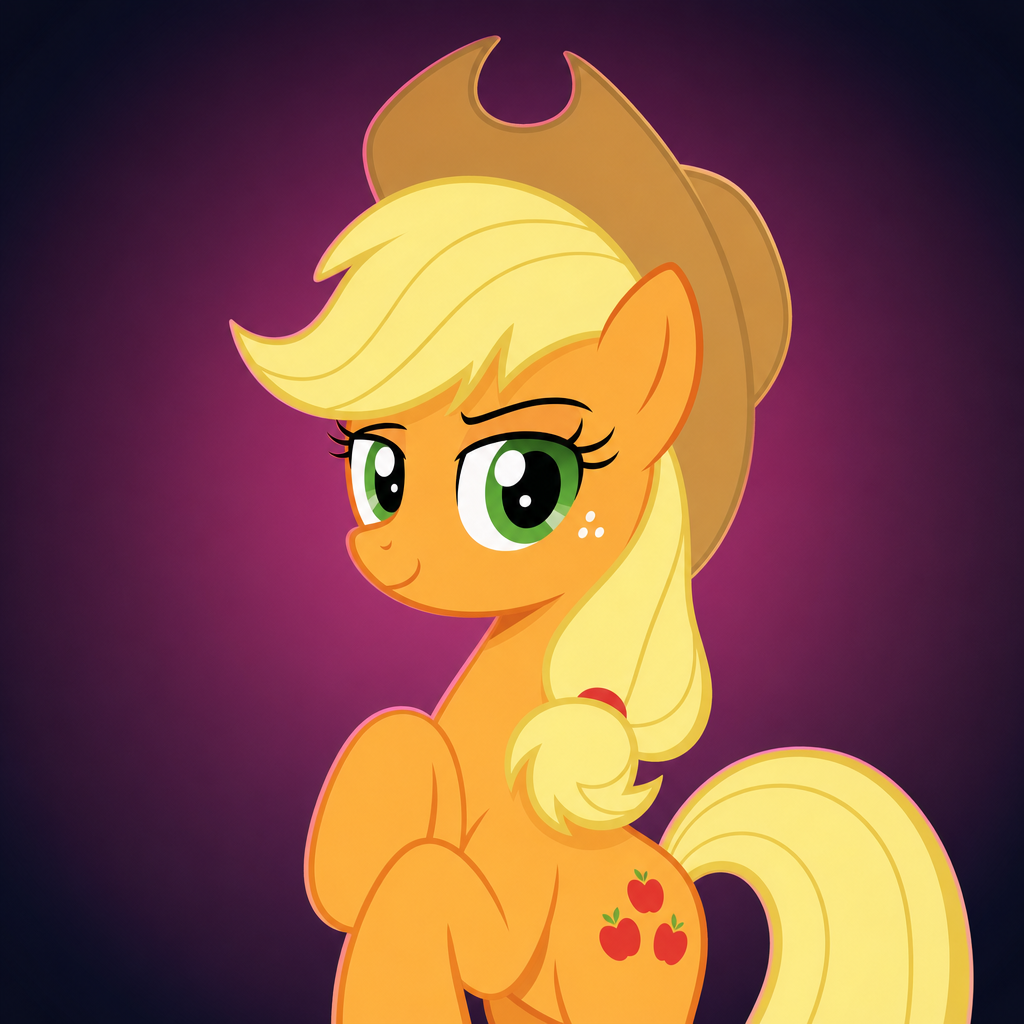
Higher preference among North American audiences
PLAYFarm / management gameplay
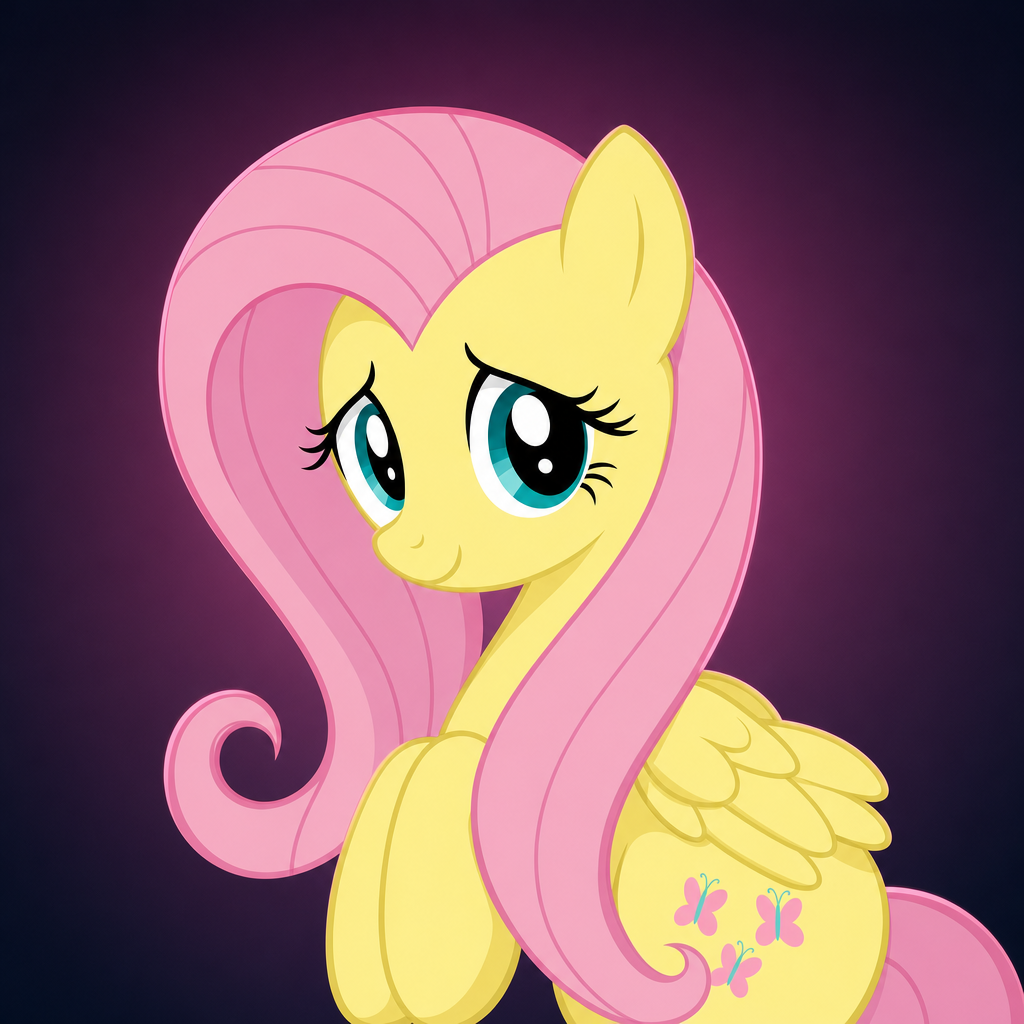
Healing-audience favorite; preferred by introverted players
PLAYPet raising / healing
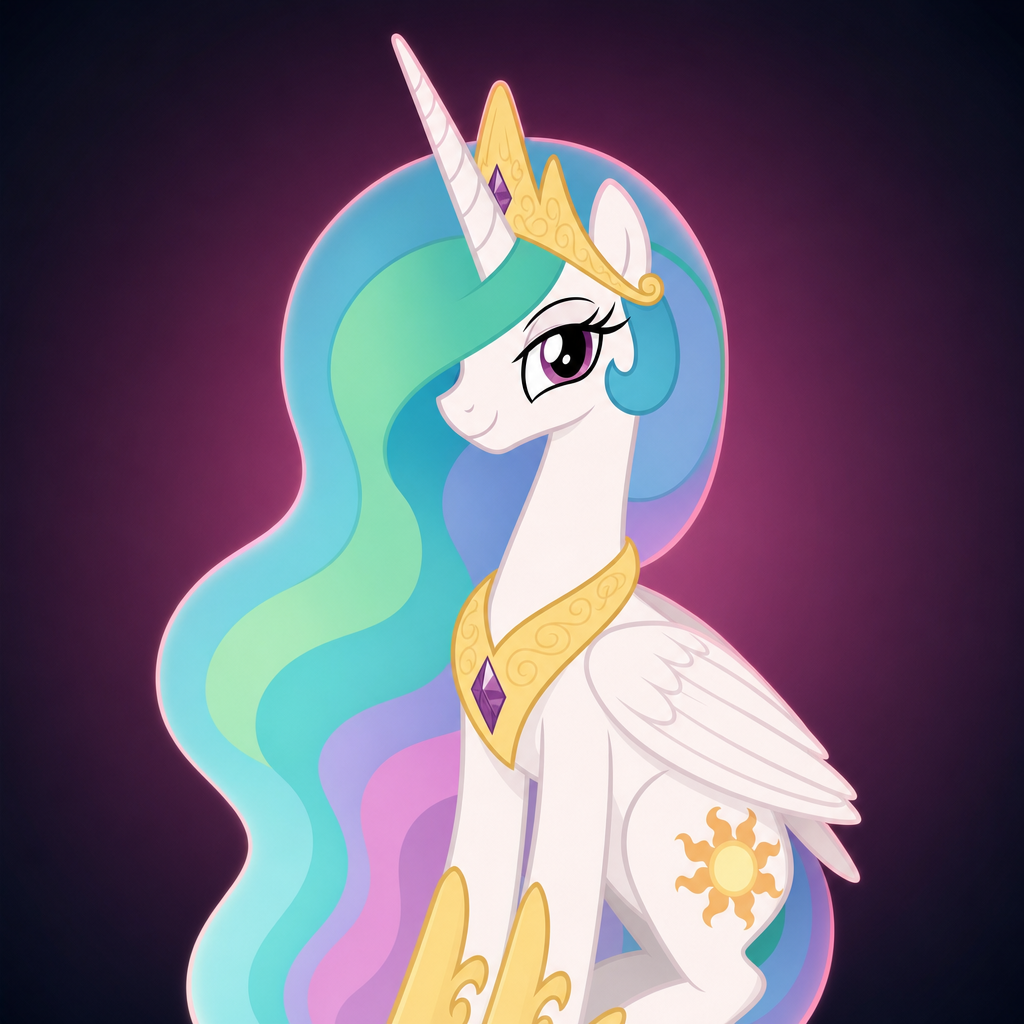
Core character in Game for Peace collab
PLAYAuthoritative character / limited skin
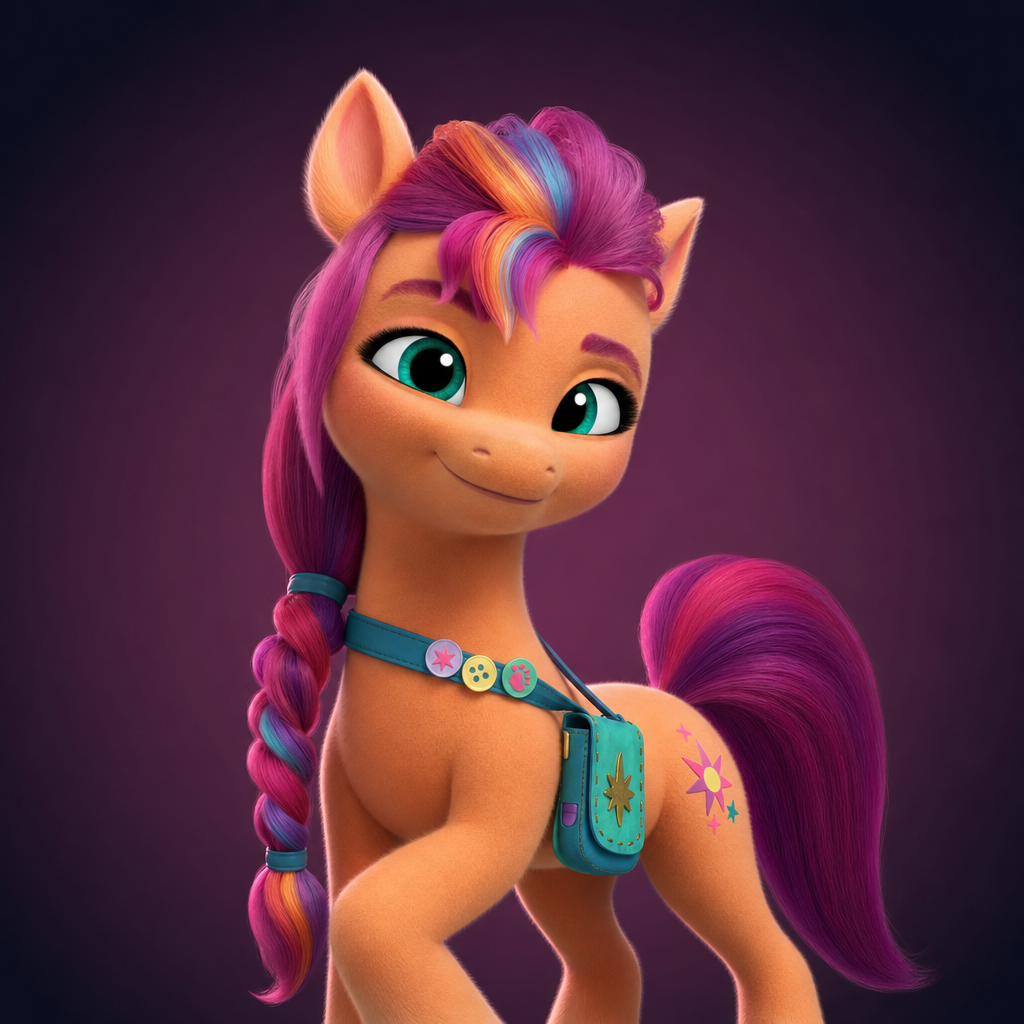
Gen Alpha preference; awareness still building
PLAYG5-exclusive collab
Benchmark cases · Latest game collabs · Collabs per year
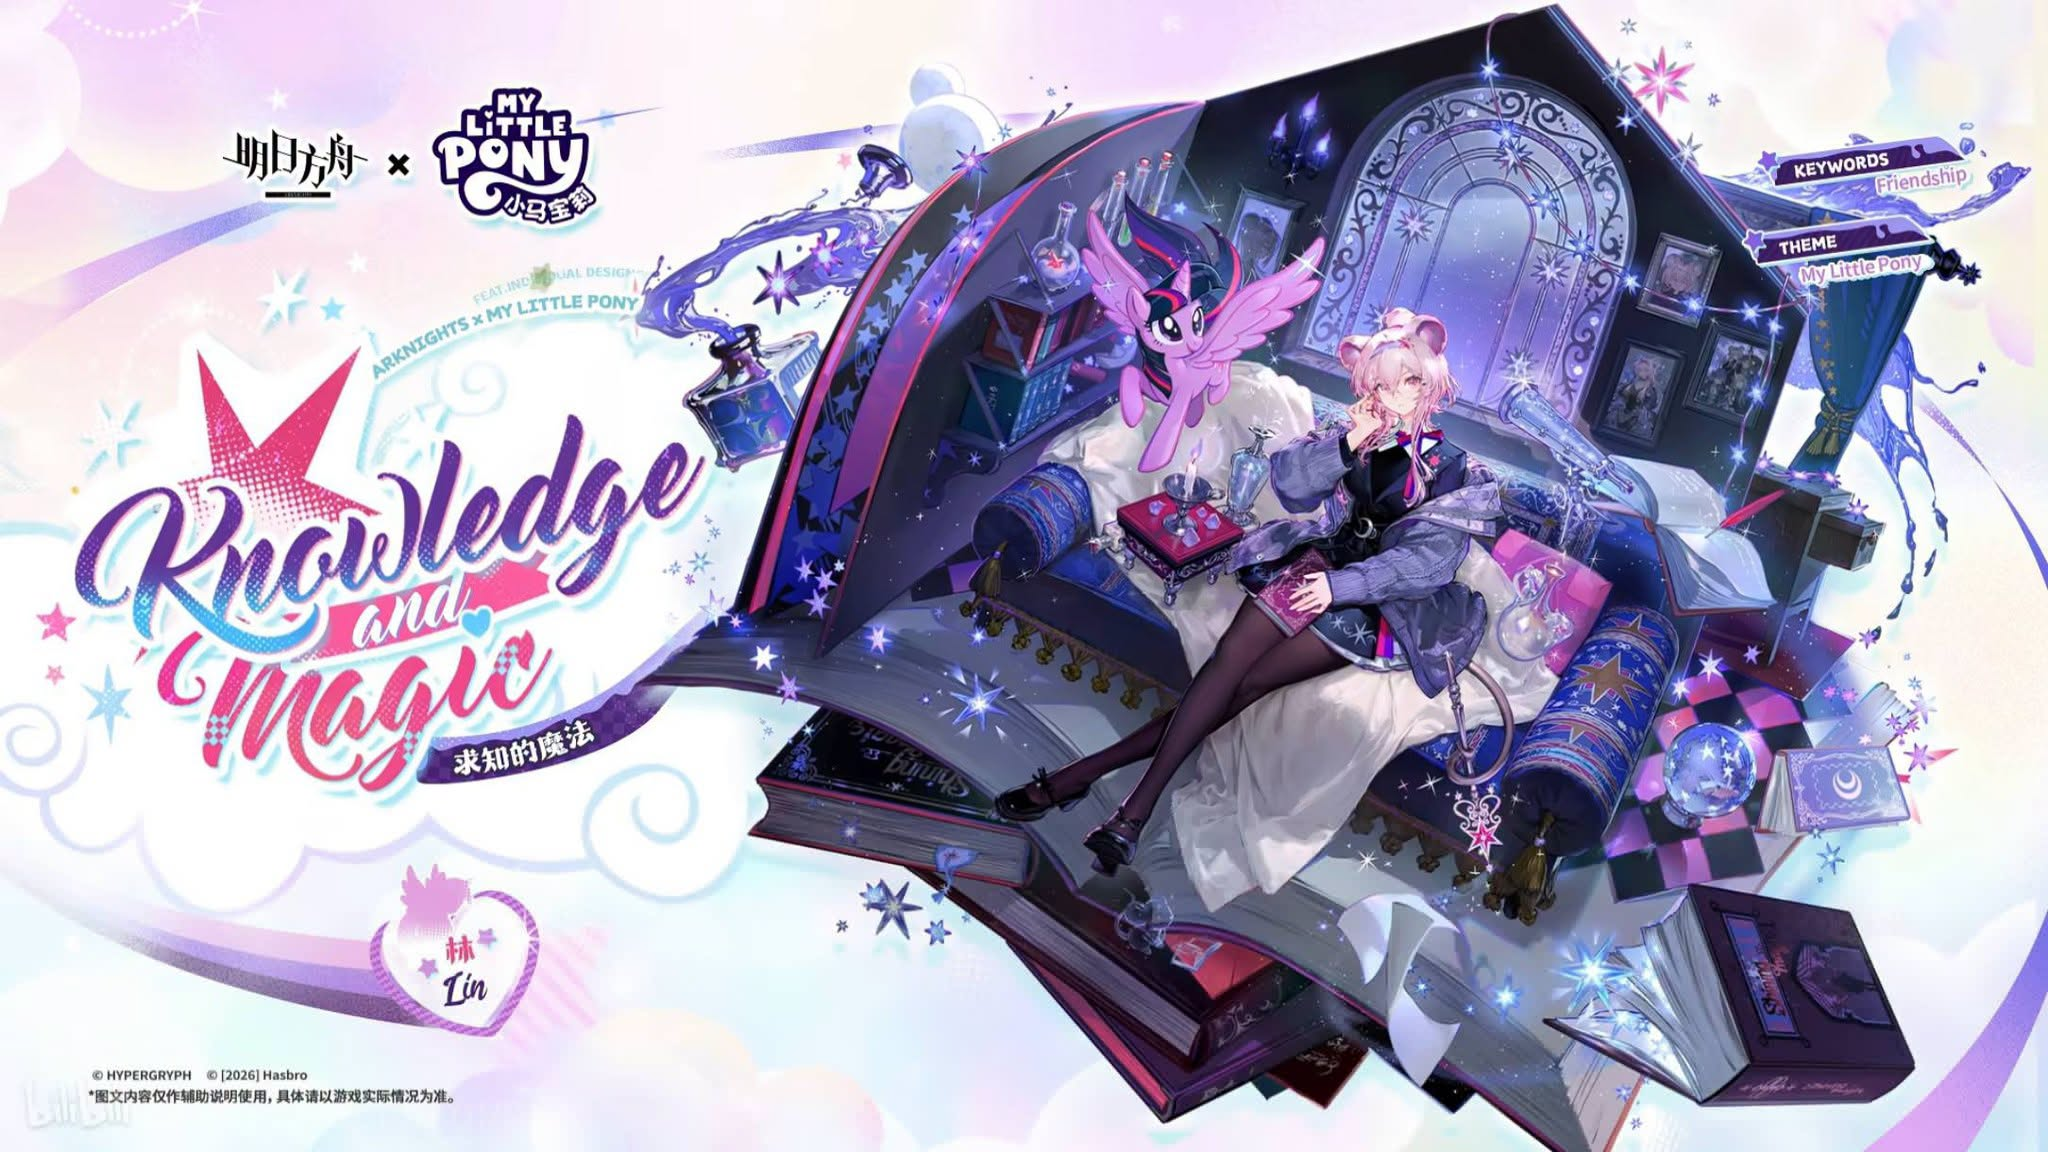
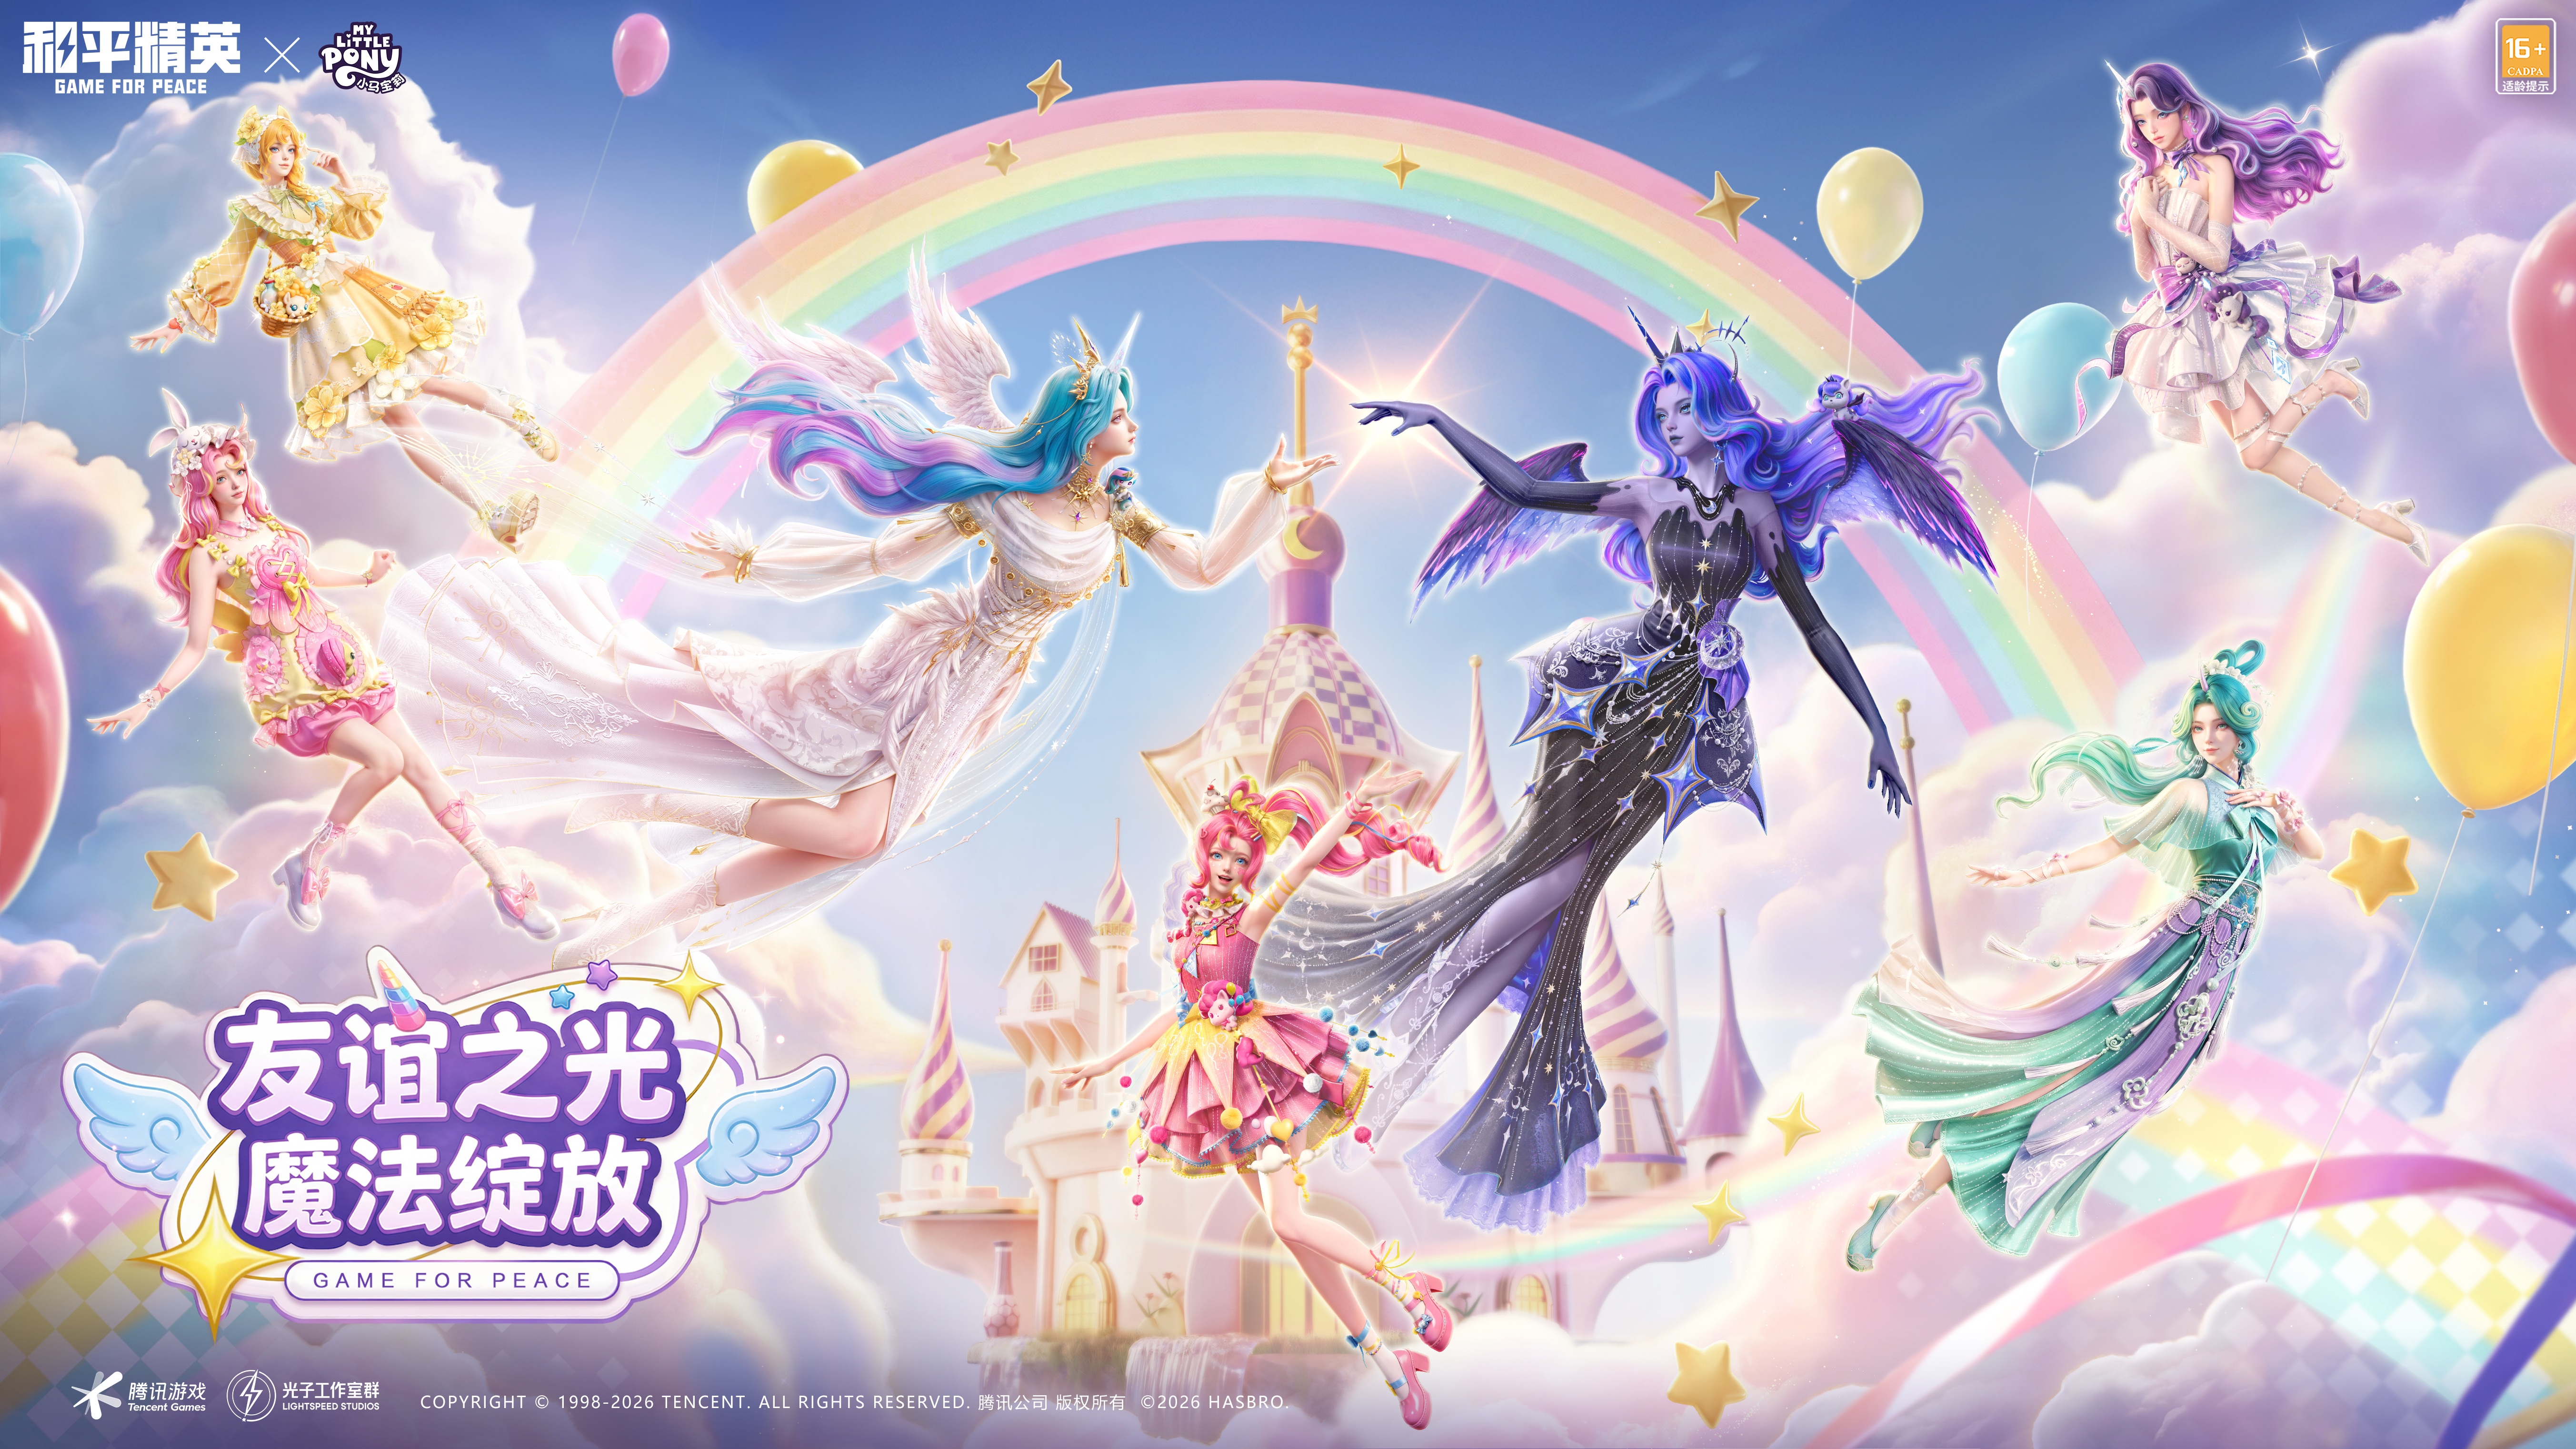
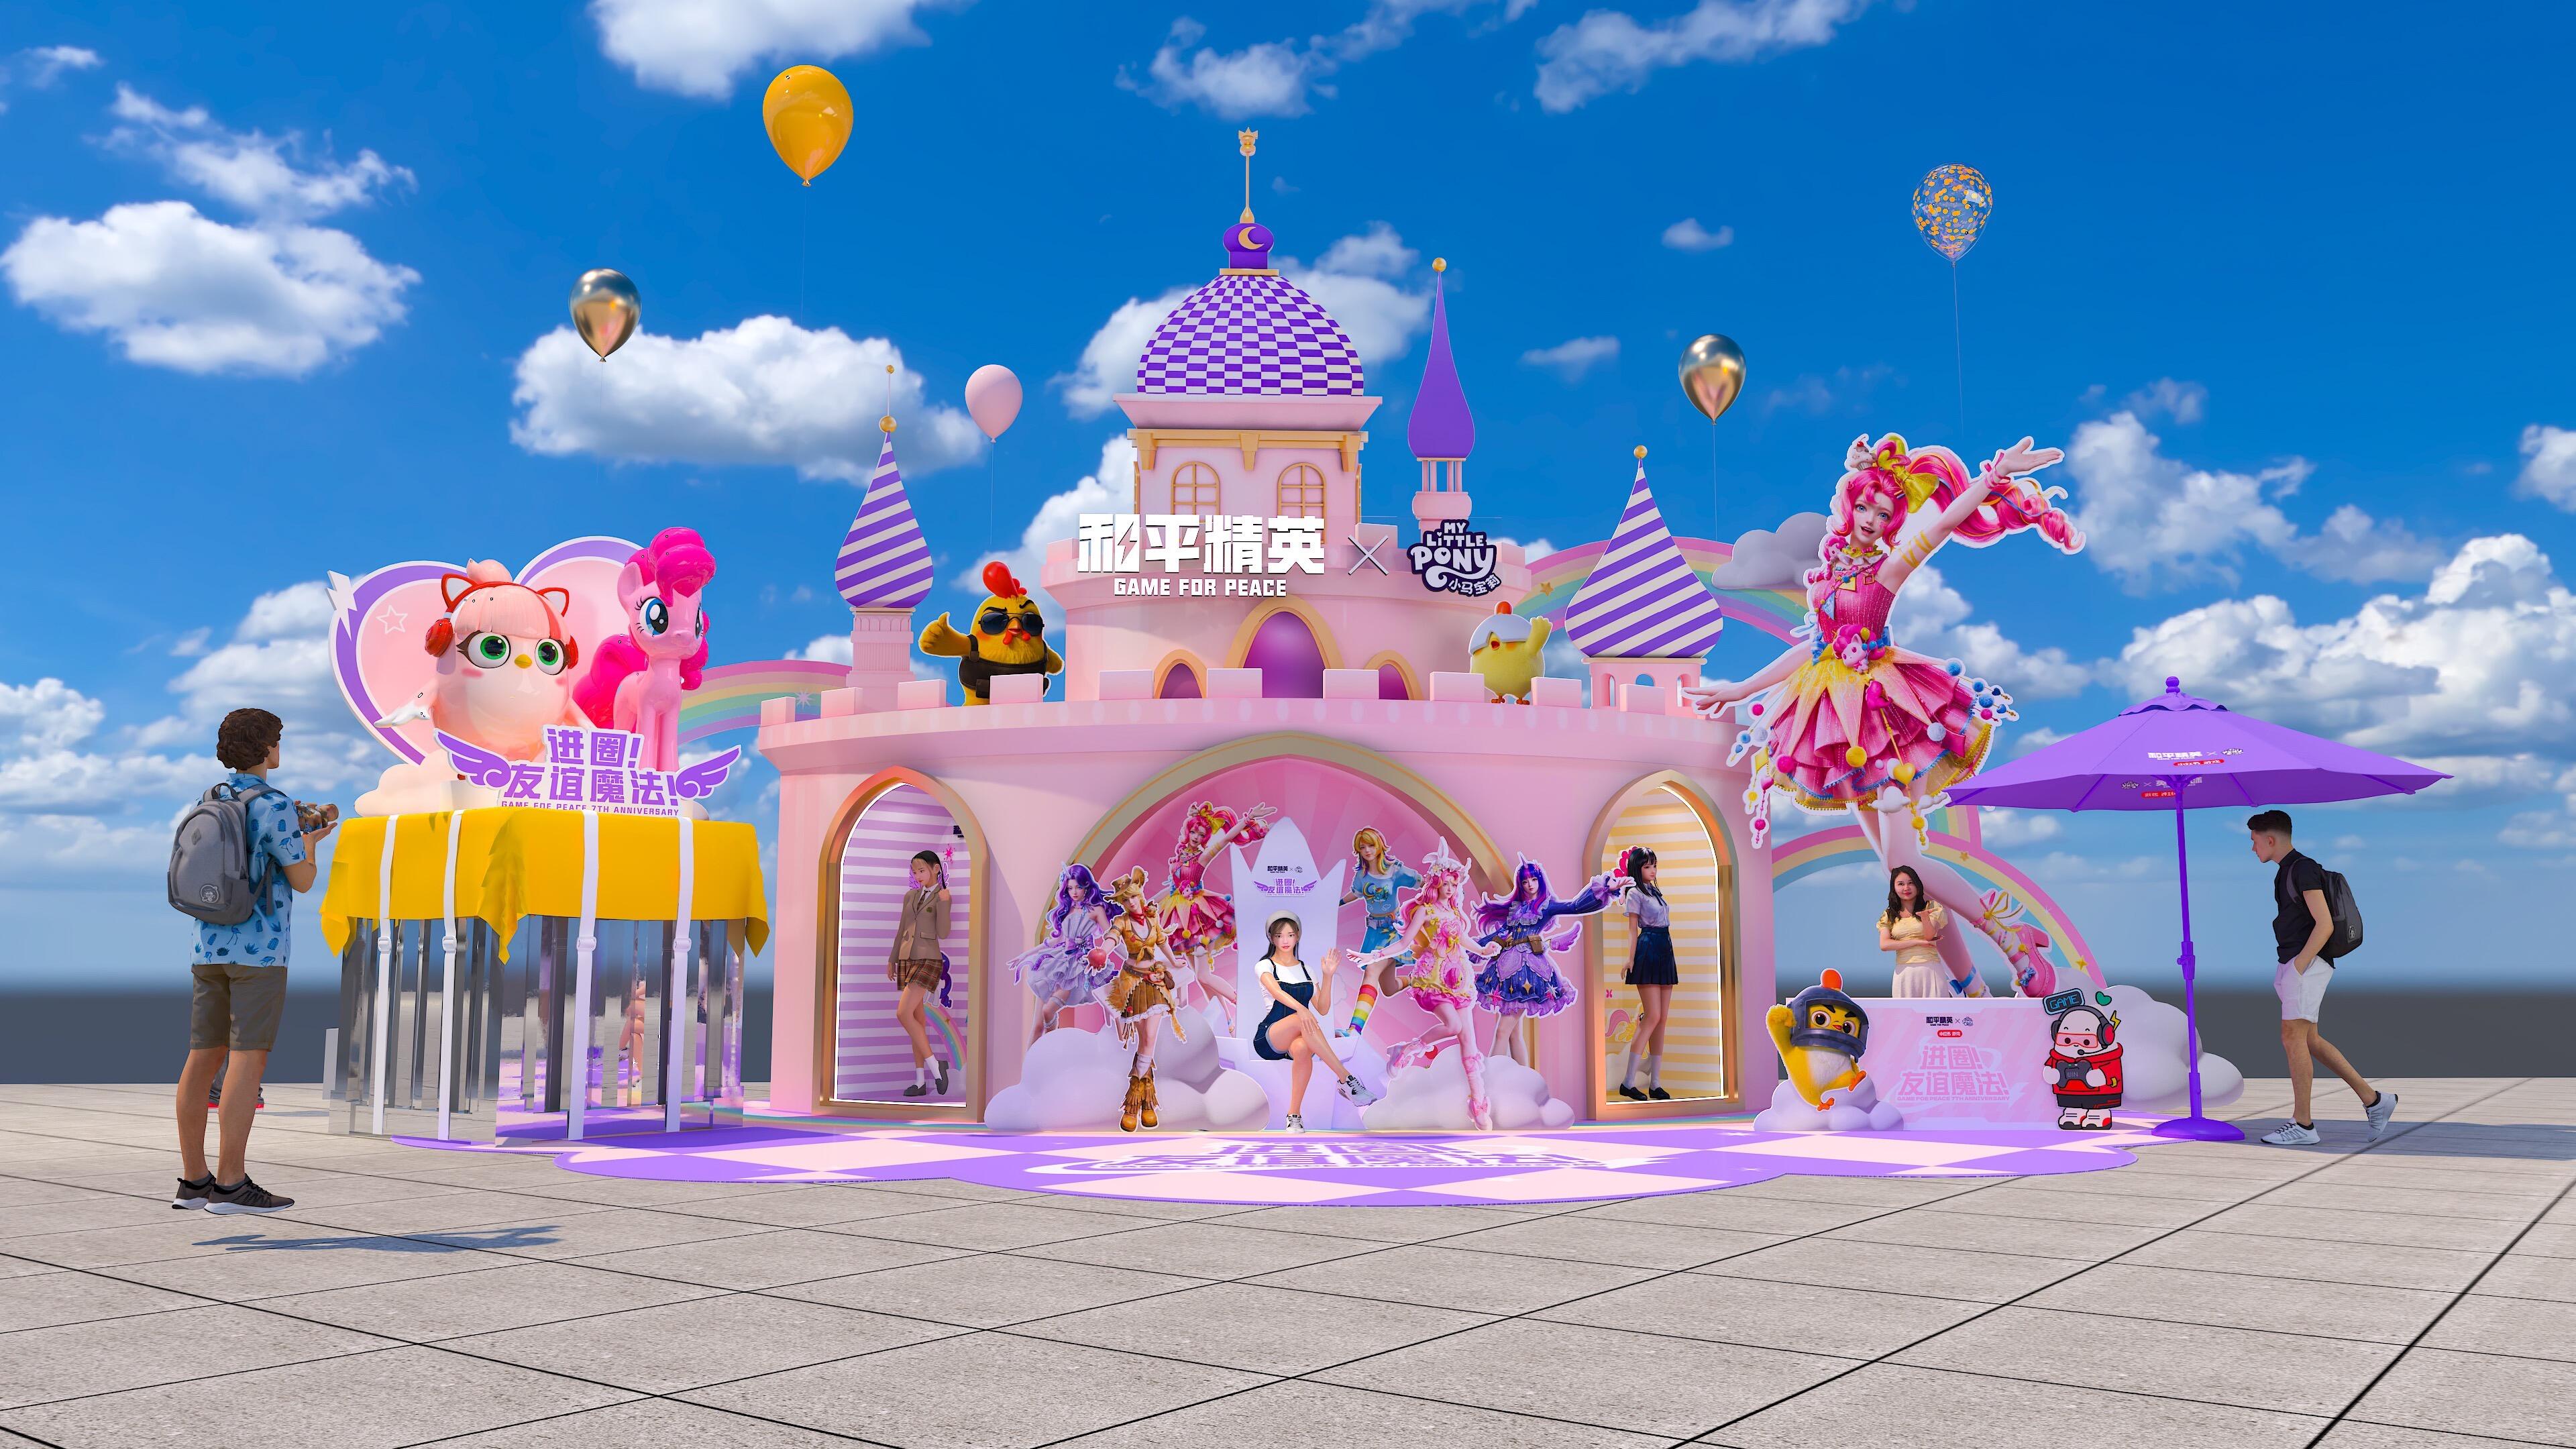
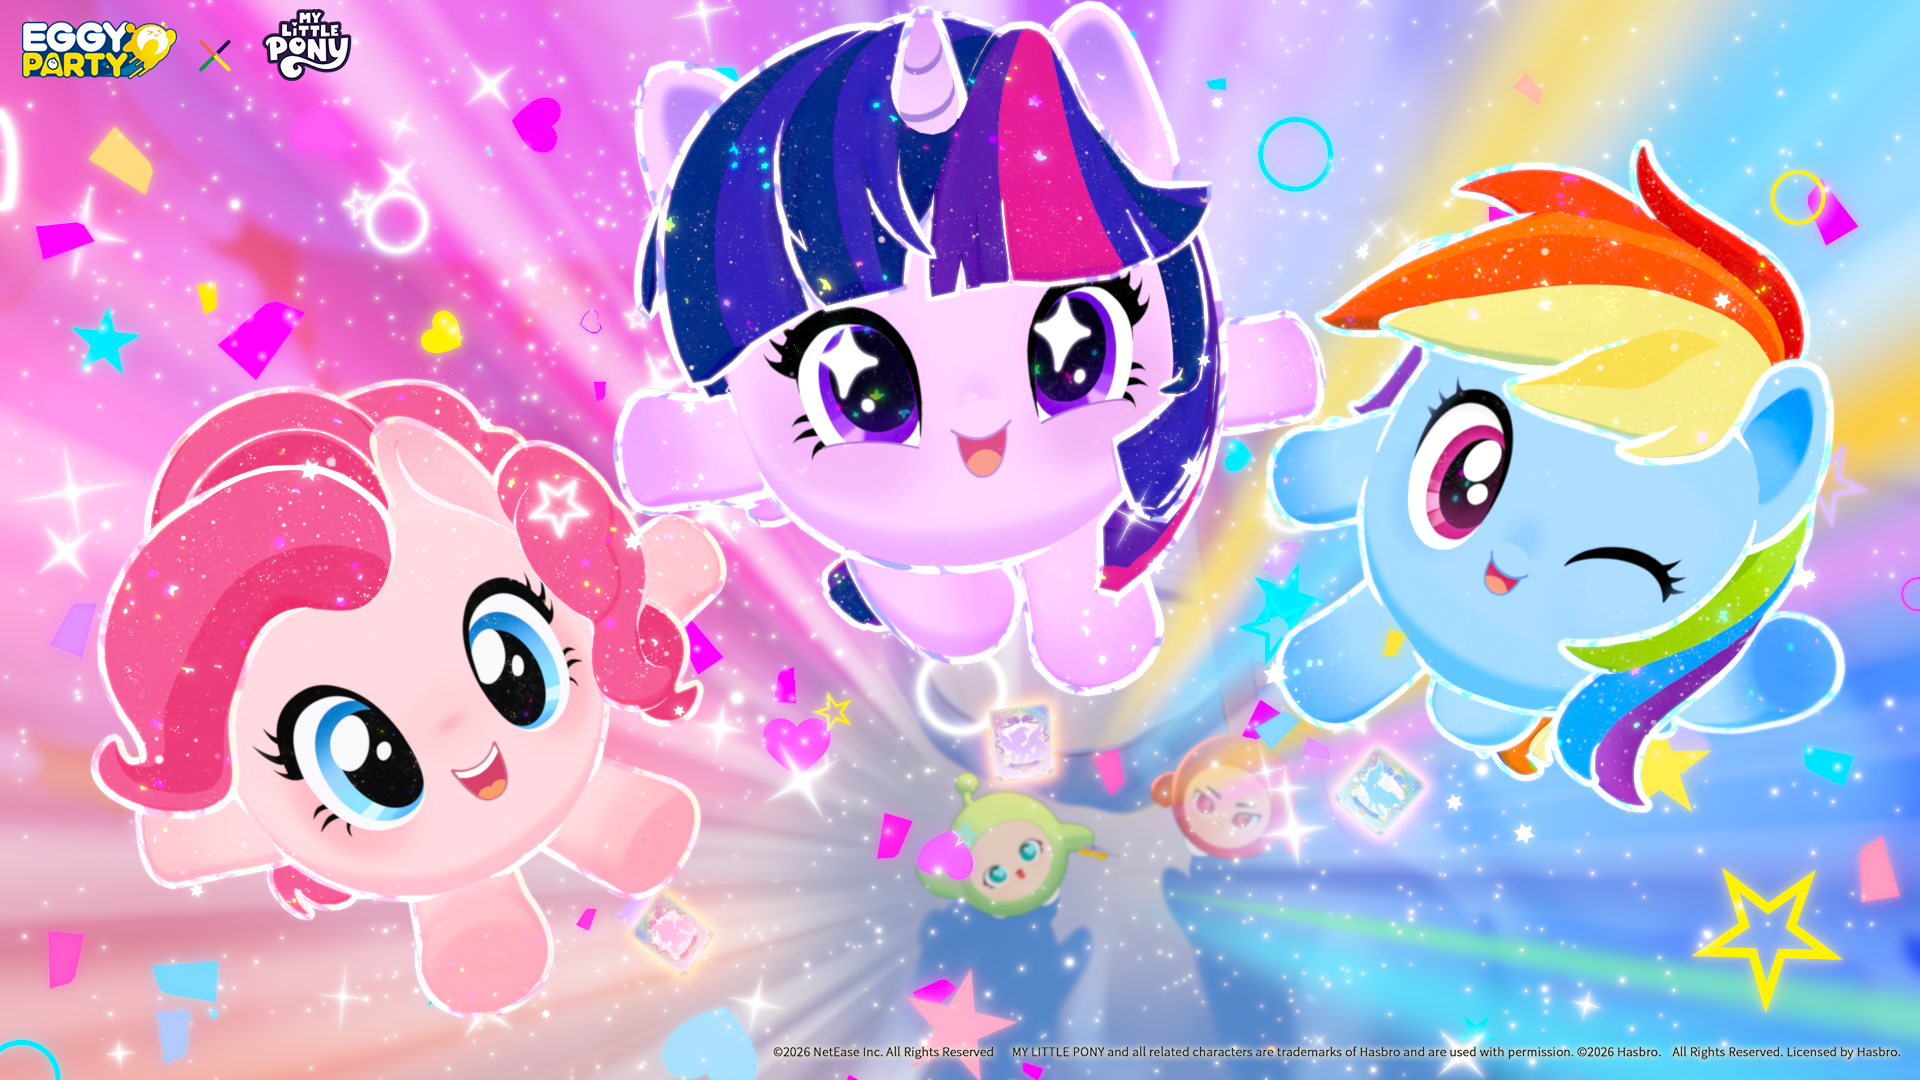
2023–2026 collab frequency grew 225% (12→39/yr); game collabs rose from 3/yr to 8+/yr; Hasbro markedly opened China game licensing
Arknights collab data (est. 25–30% DAU growth, ¥85–100M revenue) is estimated, not officially confirmed
Genre fit 1–5 · Emotional driver → Game system → Monetization
Heartopia validated: +171% revenue; friendship/healing/decoration naturally aligned
Eggy Party validated: 65% DAU participation; cute characters + social virality + low barrier
Kayou $400M+ & MTG collab; core IP monetization category
Character aesthetics + collection + social display; high potential
Honor of Kings validated: 65% DAU participation; character diversity + skin economy
Game for Peace validated: 28M pre-registrations; anthropomorphic design + female user acquisition
Roblox + Mini World validated; kids audience + creative freedom
Tonal mismatch; requires exceptional packaging capability
Life-sim + casual competitive + MOBA have multi-source data backing; collab model directly replicable
No-goForced social / isolation penalties trigger backlash
No-goCash-grab gacha pools trigger strong backlash
No-goCharacter OOC / world-building rewrites trigger community boycott
No-goForced uniformity / no personalization drives churn
2024–2026 China G4 heat surging, triple-driven by Kayou cards + Bilibili community + top-tier game collabs
2026 already saw 5+ top-tier game collabs, all achieving 60%+ DAU participation or significant revenue growth
Markedly relaxed China game licensing; Yodo1 facilitated multiple deals; high collaboration confidence
Life-sim / MOBA / battle royale / casual competitive / TCG — all five genres have multi-source data support
Amazon MGM Studios live-action film expected 2027–2028, bringing a new wave of IP heat
G5 animation/film failed to match G4 impact; new character awareness limited; IP heat reliant on G4 nostalgia
Collab frequency up 225% in 3 years; may cause audience fatigue and IP value dilution
Core fans extremely sensitive to character OOC and world-building changes; may amplify negative sentiment
2024 revenue down 17%; may affect IP investment and licensing terms
COPPA/kids protection regulations impact kids product design; screen-time limits